

Dear Spark community, below is the Q3 2026 financial report.
1. Executive Summary
Spark closed Q3 2026 with the Spark Liquidity Layer (SLL) generating stronger net revenue, supported by increased demand for crypto-collateralised lending. The quarter's strategy focused on lending against blue-chip crypto collateral through established venues and institutional lending arrangements, including SparkLend, Morpho and Anchorage Digital.
Net SLL revenue increased to $1.43M, from $0.88M in Q2, driven primarily by improved economics in the Spark Savings USDT program. Funding costs that weighed on Q2 (around $2.4M) fell to roughly breakeven in Q3 as idle reserves were reduced and returns on deployed capital improved. The captured spread rose to 0.31% for the quarter.
Distribution rewards declined to $2.25M following a Sky governance-set reduction in the distribution reward rate in July. However, distributed supply increased 4.7% during Q3 to $3.98B at quarter-end. The protocol remained profitable in every month of the quarter.
Q3 Financial Highlights
-
Gross protocol returns: $29.4M (QoQ -18%) (aggregate returns across all protocol components)
-
Net protocol returns: $5.63M (QoQ +33%) (gross returns less cost of capital)
-
Net protocol surplus: $2.55M (QoQ +300%) (gross returns less cost of capital and operating expenses)
-
Spark Protocol treasury (end of quarter): $56.6M
-
SPK token buybacks: $2.00M (capital returned via open-market purchases)
Overall, Q3 saw stronger SLL net returns alongside continued growth in Spark's Liquidity as a Service (LaaS) programs with stablecoin issuers and the Stablecoin FX Layer, both of which scaled significantly during the quarter. SLL allocations closed the quarter at their Q3 high of $2.90B.
2. Product Line Performance
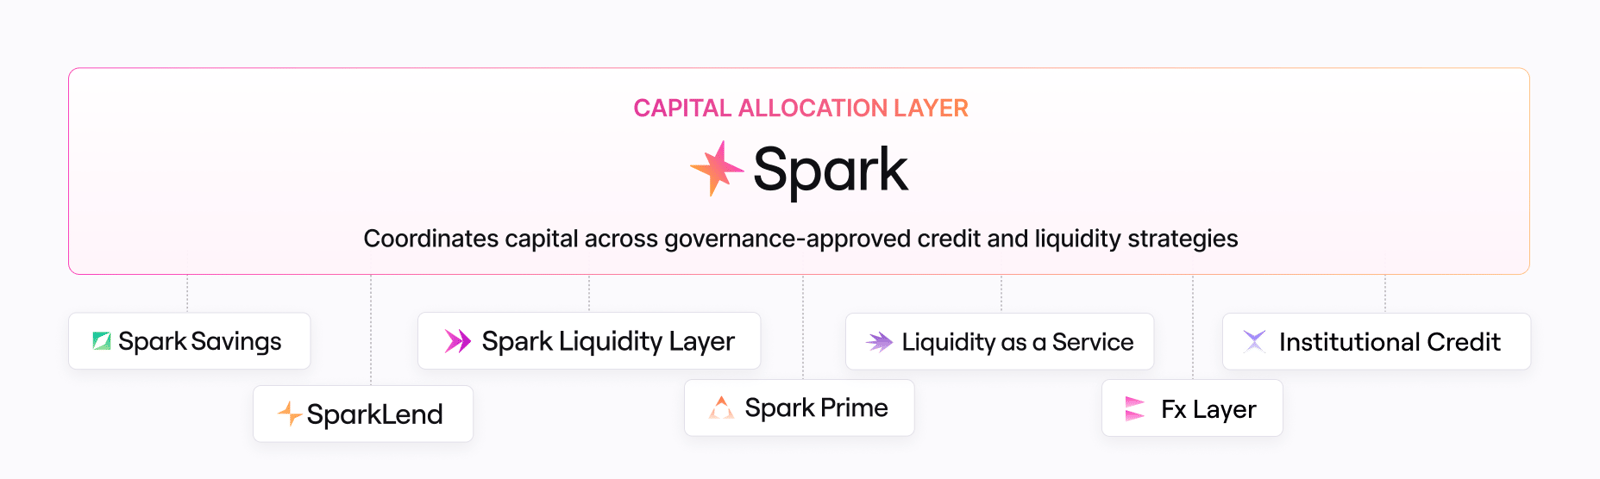
Spark comprises several components that generate protocol-level returns accrued to the treasury pursuant to governance-defined mechanisms. These are (i) Spark Liquidity Layer (ii) Distribution Rewards (iii) SparkLend (iv) Treasury Management & Financial Operations.
2.1 Spark Liquidity Layer (SLL)
The Spark Liquidity Layer is a smart-contract system that programmatically allocates capital across supported financial markets to generate returns. Thanks to this system, the protocol may generate returns subject to market conditions, smart-contract execution, and governance-defined risk parameters.
Revenue model: The protocol captures net returns across allocated positions, including spread between lending rates and funding costs where applicable, subject to market conditions.
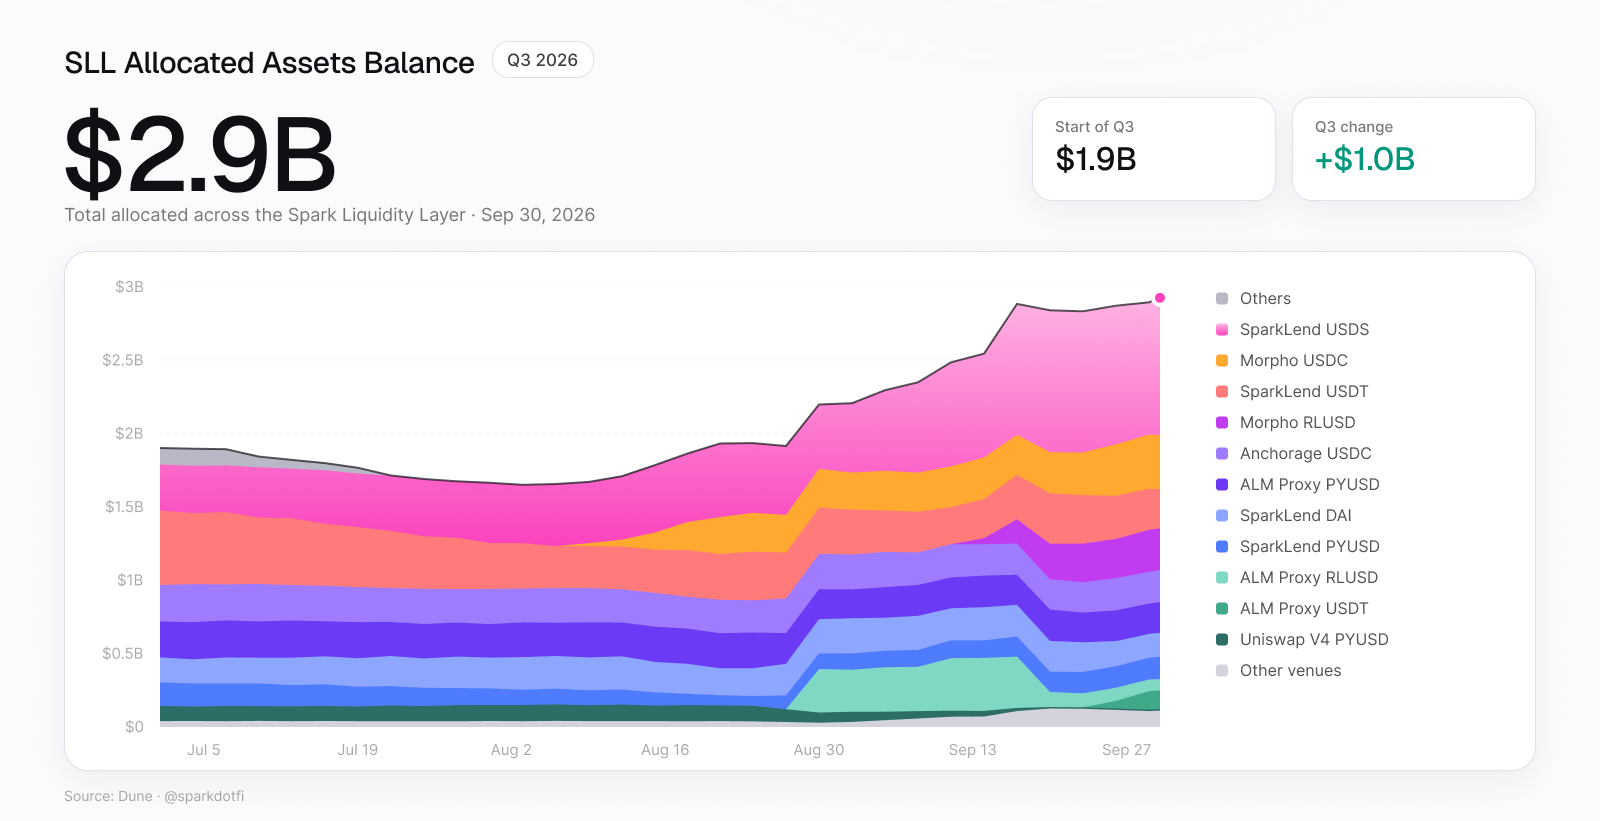
Q3 highlights: Average allocated capital was $2.06B for the quarter. Allocations grew mostly from late August, lifting the monthly average from $1.78B in July to $2.55B in September, and ended the quarter at $2.90B. Demand for borrowing against crypto collateral drove most of this growth. SLL allocations into SparkLend reached $1.58B at quarter-end, up from $1.13B, led by USDS, and allocations to Morpho vaults grew to $686M from $47M. Spark Institutional Lending, the tri-party lending structure with Anchorage, generated $3.31M in gross returns, with $212M deployed at quarter-end.
*Methodology change: from this report, Average Gross Yield and captured spread exclude the SLL's sUSDS liquidity holding, whose principal is not part of average deployment. On this basis and scope, Q2 Average Gross Yield was 3.48%, captured spread -0.06%, and net SLL revenue $0.88M, on average deployment of $2.44B.
2.2 Distribution Rewards
Spark functions as a distribution layer within the Sky ecosystem, providing users with access to Savings Vault products, including USDS-denominated savings vaults and the Sky Savings Rate. Distribution revenue reflects Spark's role in facilitating access to these savings mechanisms, where returns originate from underlying balance sheet and allocation frameworks within the Sky ecosystem.
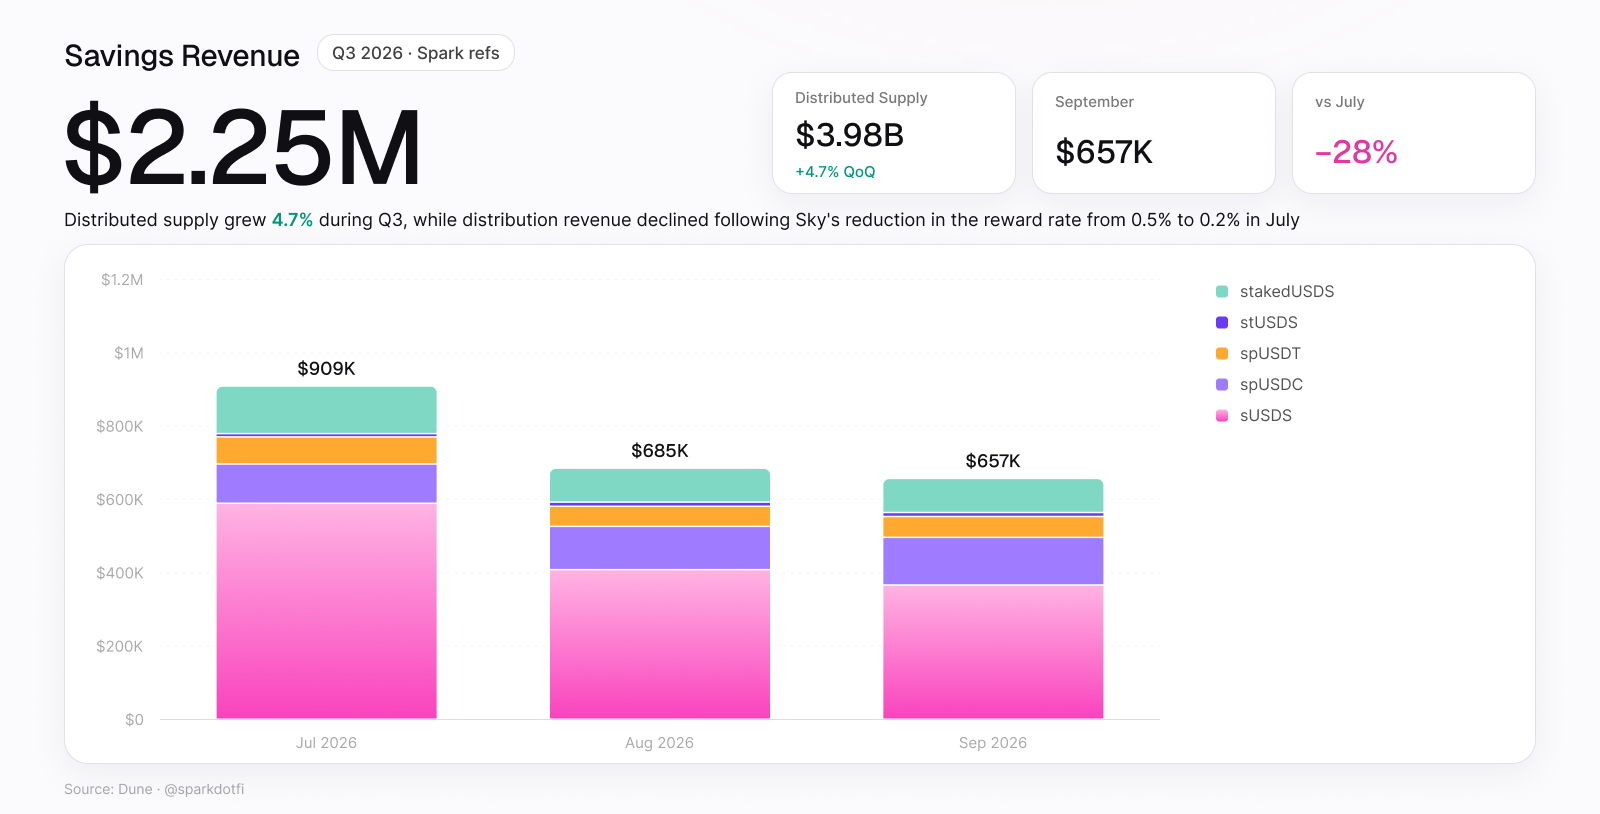
Q3 highlights: Distribution rewards were $2.25M for the quarter, down from $4.53M in Q2. The decline reflects an anticipated Sky governance-set reduction in the distribution reward rate from 0.5% to 0.2%, effective July 9, 2026. Monthly revenue moved from $0.91M in July to $0.69M in August and $0.66M in September as the new rate applied for full months. Despite the lower rate, distributed supply continued to grow, rising from $3.8B to $3.98B at quarter-end. sUSDS generated $1.37M, followed by Spark's USDC savings vaults (spUSDC and sUSDC)at $0.36M, staked USDS products (stakedUSDS and stUSDS) at $0.35M and the Spark USDT Savings Vault at $0.18M.
During the quarter, Spark launched Spark Savings USDG (spUSDG) on Robinhood Chain, where it is a yield-bearing component behind Robinhood Earn, Robinhood's USDG savings product launched on July 1. The integration extends Spark's distribution footprint to a leading consumer platform.
KPIs:
-
Net distributed sUSDS supply (end of quarter): $3.98B
-
Q3 revenue: $2.25M
2.3 SparkLend
SparkLend is a core lending protocol within the Spark ecosystem, operating as one of the largest lending platforms in DeFi (defiLlama), with only blue-chip collateral. It supports institutional borrowing activity, with liquidity supplied through the SLL as the governance-approved protocol mechanism.
Revenue model: Spark collects a reserve factor on interest accrued by borrowers.
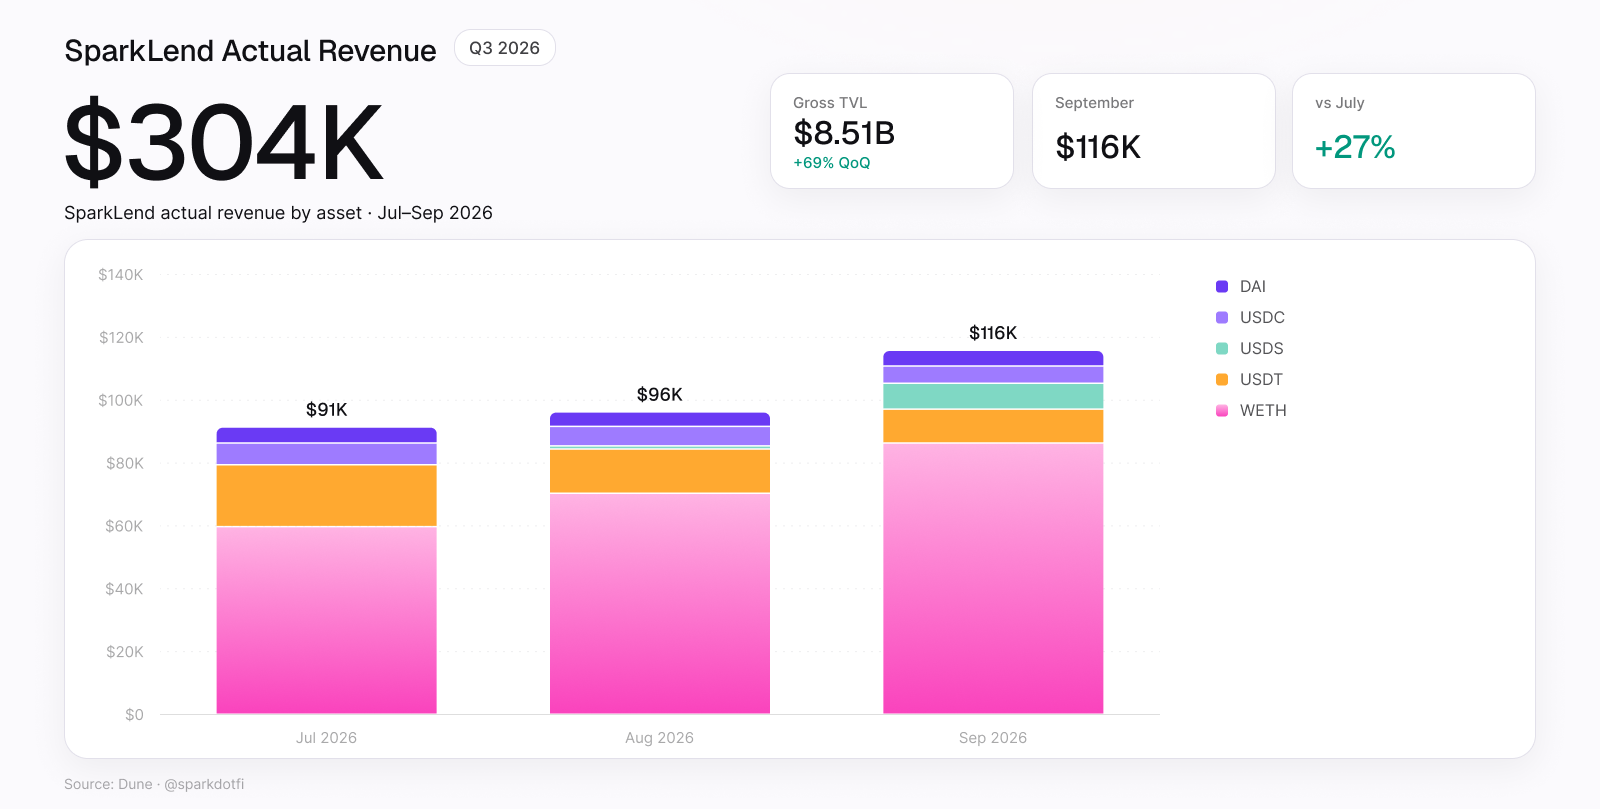
Q3 highlights: SparkLend saw stronger borrowing demand against blue-chip collateral during Q3. SparkLend's gross TVL (total supplied) reached $8.51B at quarter-end, up from $5.03B at the end of Q2, helped by a 70% rise in the ETH price. ETH looping, where users borrow WETH against wstETH and other ETH collateral, accounted for 45% of all SparkLend borrows at quarter-end, up from 39% at the end of Q2: WETH borrows reached $1.31B (about 487k ETH, up 18% in ETH terms), nearly all associated with looping positions. SLL allocations into SparkLend reached $1.58B at quarter-end across USDS, USDT, DAI, PYUSD and USDC, up from $1.13B at the end of Q2, with USDS allocations rising to $920M from $313M. Reserve factor revenue rose to $304k for the quarter from $245k in Q2, increasing each month from $92k in July to $96k in August and $116k in September, led by WETH borrowing.
KPIs:
-
SparkLend gross TVL (end of quarter): $8.51B
-
SparkLend SLL deployment (end of quarter): $1.58B
-
Q3 revenue (reserve factor on yield, excluding SLL): $304k
-
Q2 revenue (reserve factor on yield, excluding SLL): $245k
2.4 Treasury Management & Financial Operations
Spark's treasury represents the protocol's operational capital. It pays for the protocol's operating expenses and provides the junior capital required under Sky’s risk framework to access Sky credit line. It serves as a core component of Spark's risk framework, providing capital support and helping absorb potential losses. The September settlement with Sky of $4,218,121, settled to the treasury on October 12, 2026, is recognized as a receivable at quarter-end on the treasury statement.
Revenue model: The protocol may generate returns on treasury assets through Sky's savings rate and other financial operations.
Q3 highlights: During Q3, the treasury generated $442k in net returns, comprising $421k of USDS-denominated savings yield on the treasury balance and a $21k realized gain on the sale of the treasury's crypto asset holdings, up from $332k in Q2.
The protocol continued its SPK token buyback program, allocating 2M in USDS to open-market purchases of SPK and acquiring 106.89M SPK across 1,996 fills over the quarter, up from $1.31M and 58.26M SPK in Q2.
The accrued depositor-yield liability of the Spark Savings Vaults stood at $4.66M as of September 30. It covers the vaults whose depositor yield is settled through the treasury (spUSDT, spPYUSD and spUSDG), and the quarter-start figure is shown on the same basis.
3. Consolidated P&L
This section provides a summary of Spark's total revenues, costs, and net results across all protocol components for the quarter. It combines returns generated through the Spark Liquidity Layer (SLL), distribution rewards, SparkLend reserve factor revenue, treasury operations, curator fees and grants, net of the cost of capital and operating expenses, to illustrate Spark's protocol-level net results for the quarter.
Spark recorded $29.36M in gross revenue and $2.55M in net protocol surplus during Q3, after $26.81M in total protocol expenses.
Basis of presentation: Q2 comparatives in this report are presented on the Q3 basis. Rewards on protocol-owned sUSDS held by the SLL are excluded from distribution rewards.
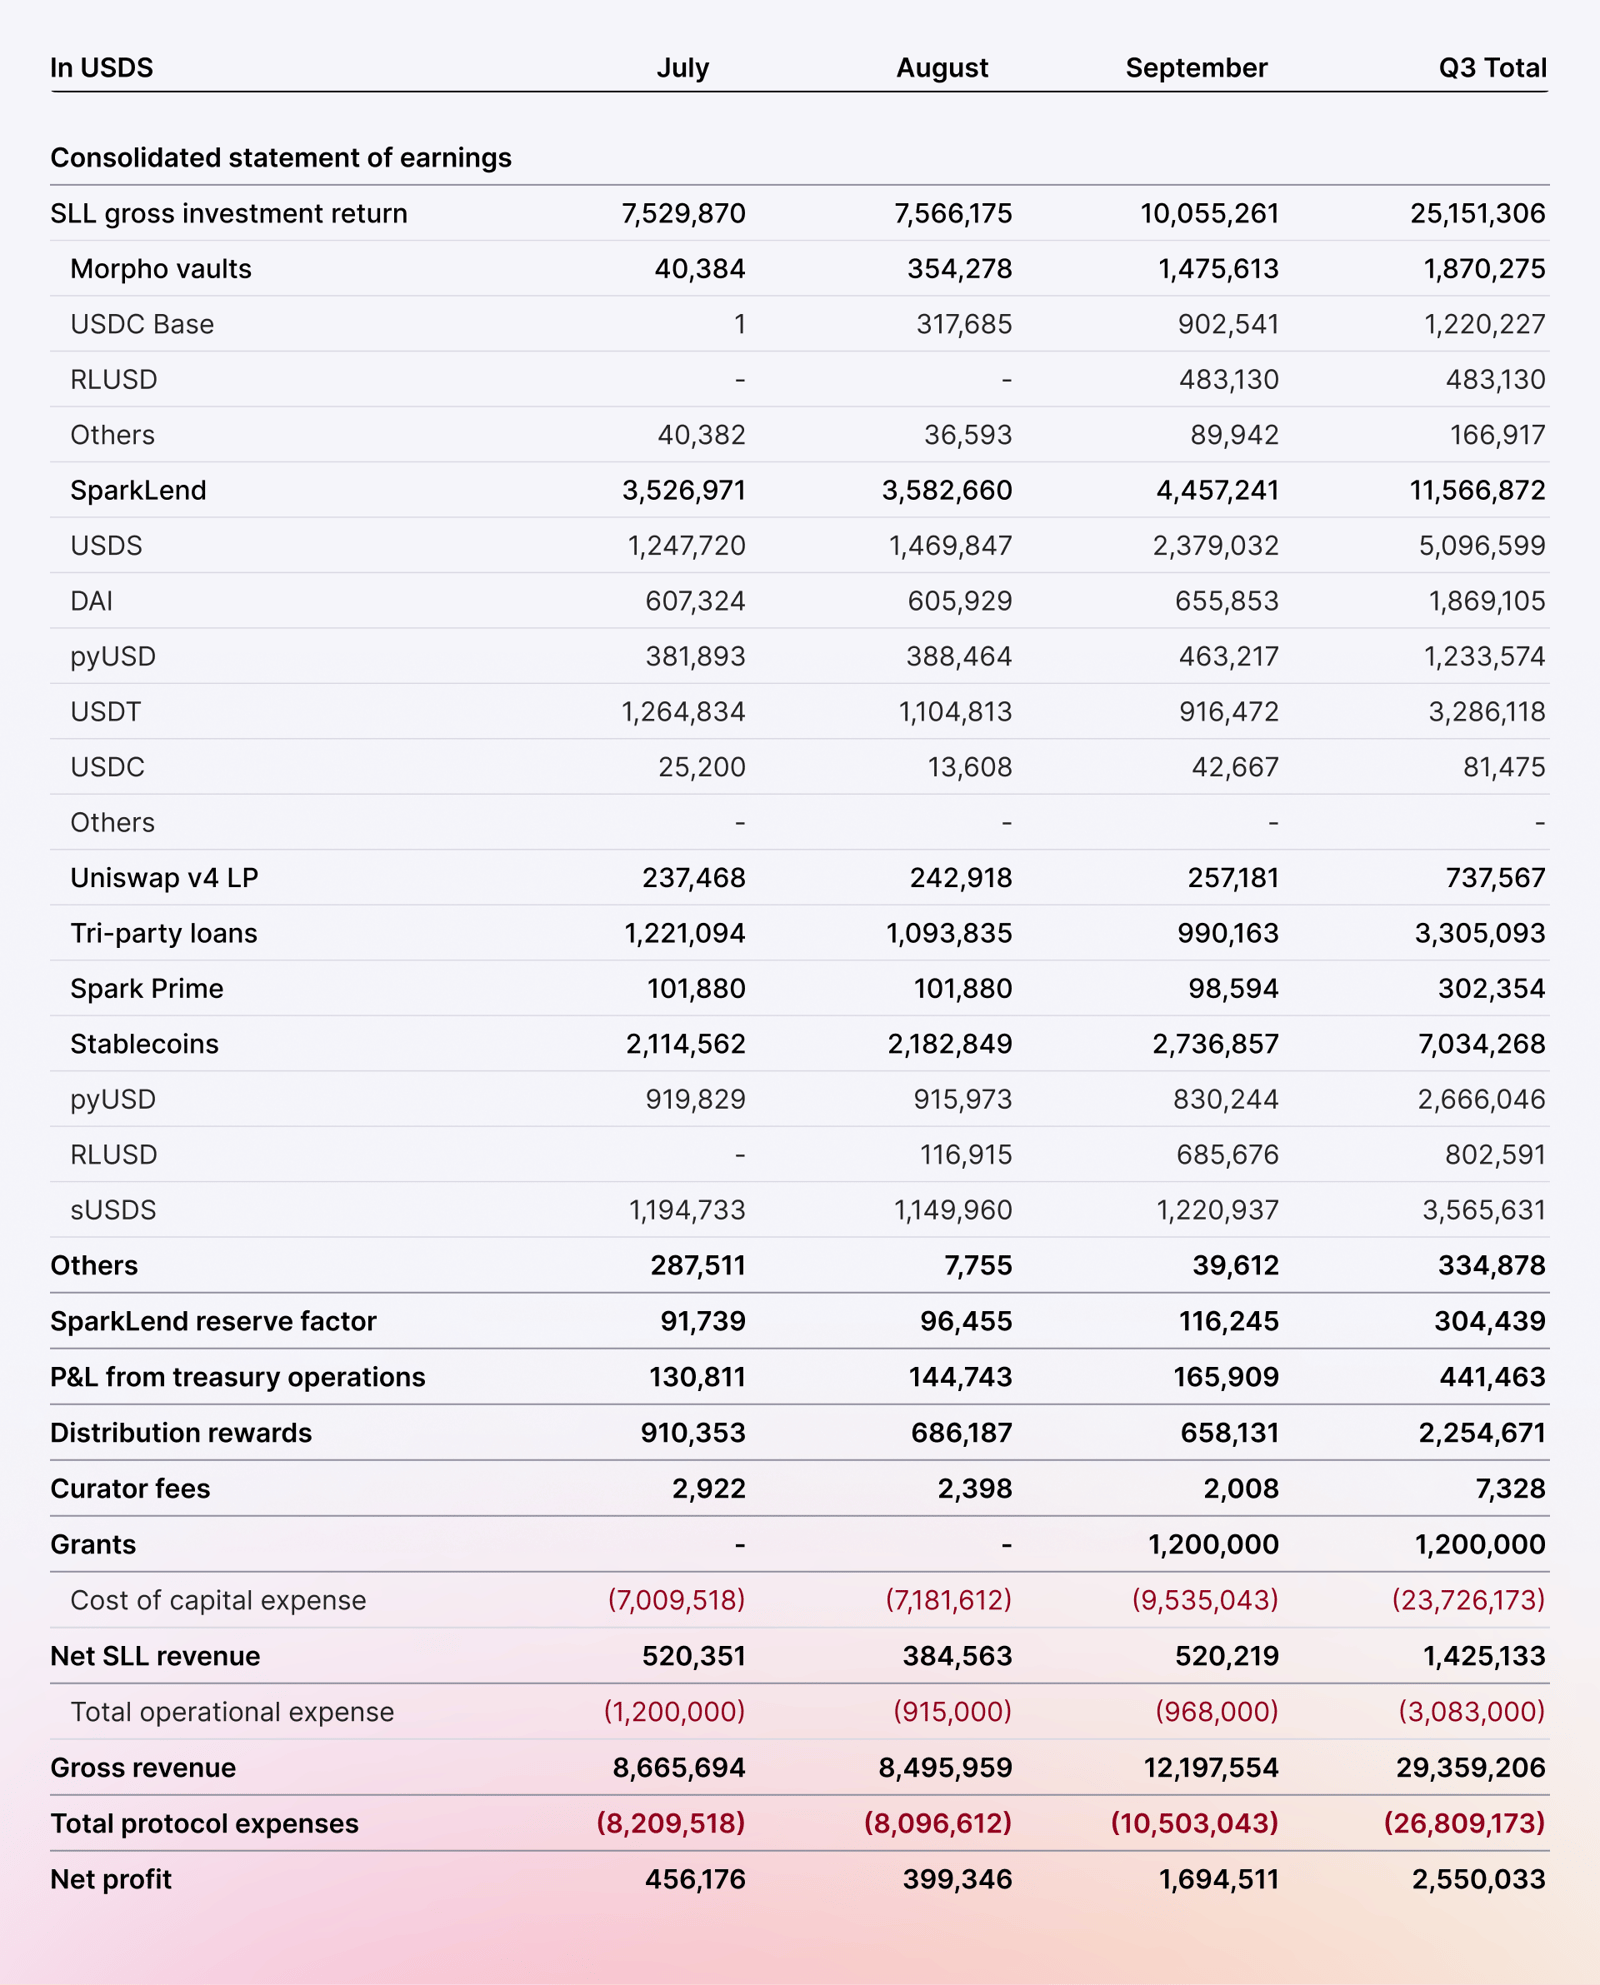
Accounting note: The consolidated statement of earnings represents Spark's internal, accrual-based estimate of revenues, costs, and net results for the quarter, based on protocol-level data and internal calculations. Settlement flows from Sky may differ in timing or amount and are reconciled over subsequent settlement periods. Figures are presented as of September 30, 2026, based on Dune data available at publication. Gross figures scale with Savings Vault deposits and the USDS issued against them and are matched by corresponding cost of capital; net measures are the primary indicators of underlying performance.
4. Consolidated Balance Sheet
Spark's treasury position as of September 30, 2026, expressed in USDS terms.
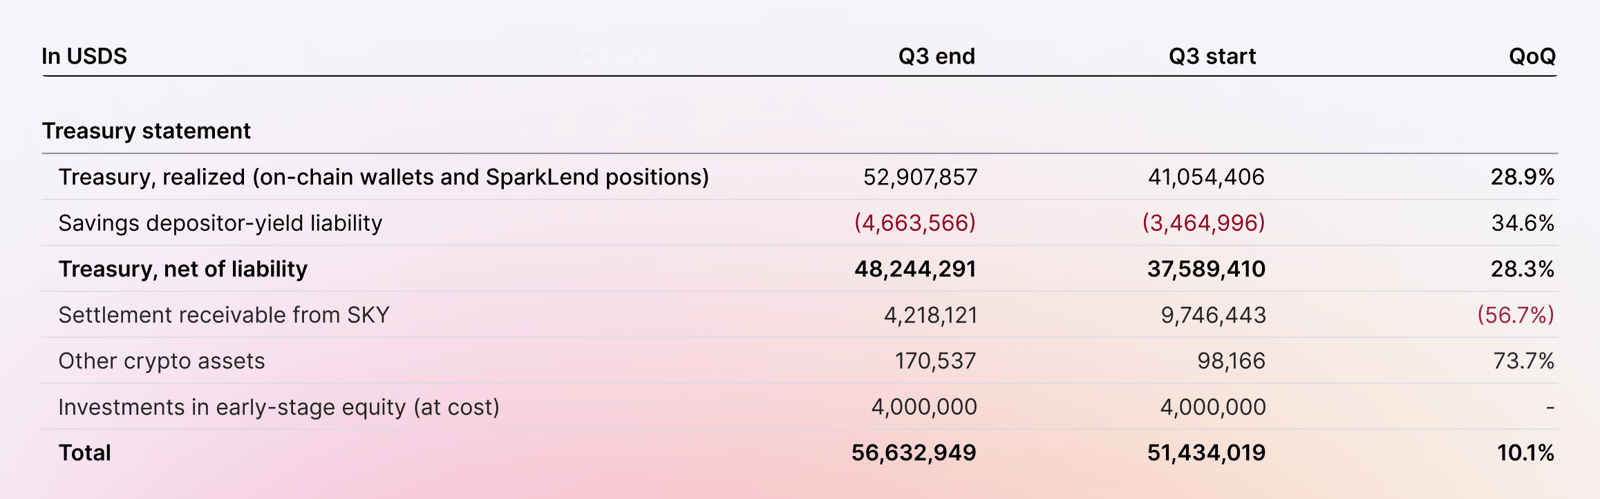
Notes: The statement reflects positions held onchain, depositor obligations credited by the Savings Vaults, and settlement receivables. Treasury figures follow Dune query 6656460, with quarter-end balances verified onchain. The settlement receivable at quarter-end is the September 2026 settlement with Sky, settled on October 12, 2026. The depositor-yield liability covers spUSDT, spPYUSD and spUSDG, with the quarter-start figure on the same basis. Spark Savings USDC is self-contained within the SLL allocation but is funded by its own depositors. Its balances are excluded from reported SLL allocations, and and its depositor obligations do not accrue as liabilities to the treasury. Accordingly, from this report, spUSDC is excluded from the depositor-yield liability, at quarter-end and at quarter start.
5. Quarterly Insights and Commentary
Growth drivers
Q3 was defined by a recovery in lending demand and Spark's ability to capture it. As borrowing against crypto collateral picked up, the SLL grew its allocations into SparkLend, Morpho vaults and Spark Institutional Lending, and the captured spread rose to 0.31% for the quarter. Spark's Liquidity-as-a-Service programs with leading issuers, PayPal's PYUSD and Ripple's RLUSD, grew to $754M. The Stablecoin FX Layer handled $14.9B of volume in its first full quarter, establishing Spark as a core venue for stablecoin conversion on Ethereum. Spark Savings USDG brought Spark's savings infrastructure to Robinhood Earn, and the Spark Savings USDT program moved from a period of investment to roughly breakeven, with growing traction among institutional allocators.
Challenges
Distribution rewards fell to $2.25M from $4.53M following a previously anticipated Sky governance-approved reduction in the distribution reward rate in July, although distributed supply continued to grow during the quarter. Gross protocol returns declined to $29.4M, mainly because returns on the SLL's stablecoin reserve holdings, which are largely matched by funding costs, declined alongside distribution rewards. Average allocated capital was lower than in Q2 at $2.06B, although allocations rose through the quarter to $2.90B at quarter-end. The higher spread captured in the SLL offset the decline in distribution rewards, and the protocol remained profitable every month, with net protocol surplus ranging from $399k to $1.69M monthly.
Risk management
During Q3, Spark maintained its focus on blue-chip assets and venues. The SLL remained predominantly allocated to over-collateralized lending against crypto collateral, onchain through SparkLend and Morpho and offchain through the Anchorage tri-party structure, and the protocol grew its allocations within that perimeter as lending demand recovered. The protocol's treasury stood at $56.6M at quarter-end, continuing to serve as junior capital for the system and providing an additional buffer against adverse market conditions.
Appendix
Spark addresses:
-
Spark Treasury: 0x3300f198988e4C9C63F75dF86De36421f06af8c4
-
Spark Treasury (SAF): 0xEabCb8C0346Ac072437362f1692706BA5768A911
-
SparkLend reserve factor collector: 0xb137E7d16564c81ae2b0C8ee6B55De81dd46ECe5
-
Spark Foundation: 0x92e4629a4510af5819d7d1601464c233599ff5ec
-
Spark operations: 0x2e1b01adabb8d4981863394bea23a1263cbaedfc
-
SPK buyback: 0x797B010E0BABb493b8DEDD6F6ce5cc72778C2BF3
-
Spark Liquidity Layer (Ethereum): 0x1601843c5e9bc251a3272907010afa41fa18347e
-
Spark Liquidity Layer (Base): 0x2917956eFf0B5eaF030abDB4EF4296DF775009cA
-
Spark Liquidity Layer (Unichain): 0x345E368fcCd62266B3f5F37C9a131FD1c39f5869
-
Spark Liquidity Layer (Arbitrum): 0x92afd6F2385a90e44da3a8B60fe36f6cBe1D8709
-
Spark Liquidity Layer (Optimism): 0x876664f0c9Ff24D1aa355Ce9f1680AE1A5bf36fB
-
Spark Liquidity Layer (Avalanche): 0xecE6B0E8a54c2f44e066fBb9234e7157B15b7FeC
-
Treasury data: https://dune.com/queries/6656460
Data sources:
-
Product architecture: Spark protocol documentation
-
Financial statements & treasury data: Spark Finance internal financial records (Q3 2026).
-
onchain data: Dune Analytics (links provided throughout the report).
Disclaimers
This communication is provided for informational purposes only, without warranty of any kind, express or implied, including but not limited to implied warranties of merchantability, non-infringement, or fitness for a particular purpose. This communication has been prepared based on data and information that has not been independently verified and Phoenix Labs makes no representations about the accuracy of the information or appropriateness for a given situation. This content is not intended or offered as advice of any kind including financial, investment, legal, regulatory, or tax advice, and users should seek qualified professional advice where appropriate. References to assets or protocols are provided for informational purposes only, and this communication is not an offer to sell, solicitation of an offer to buy, or inducement or recommendation to engage with any asset or protocol. For the avoidance of doubt, Phoenix Labs prepares this report solely in its capacity as a nested contributor and does not control, own, or operate Spark or its protocol treasury. This communication has not been prepared by a professional accounting service provider, and figures and calculations may not conform to GAAP or other international standards for financial reporting. This communication is not intended for residents or nationals of the United Kingdom, or for other prohibited or restricted jurisdictions and persons including those listed on US, EU, UK, or UN sanctions lists.