
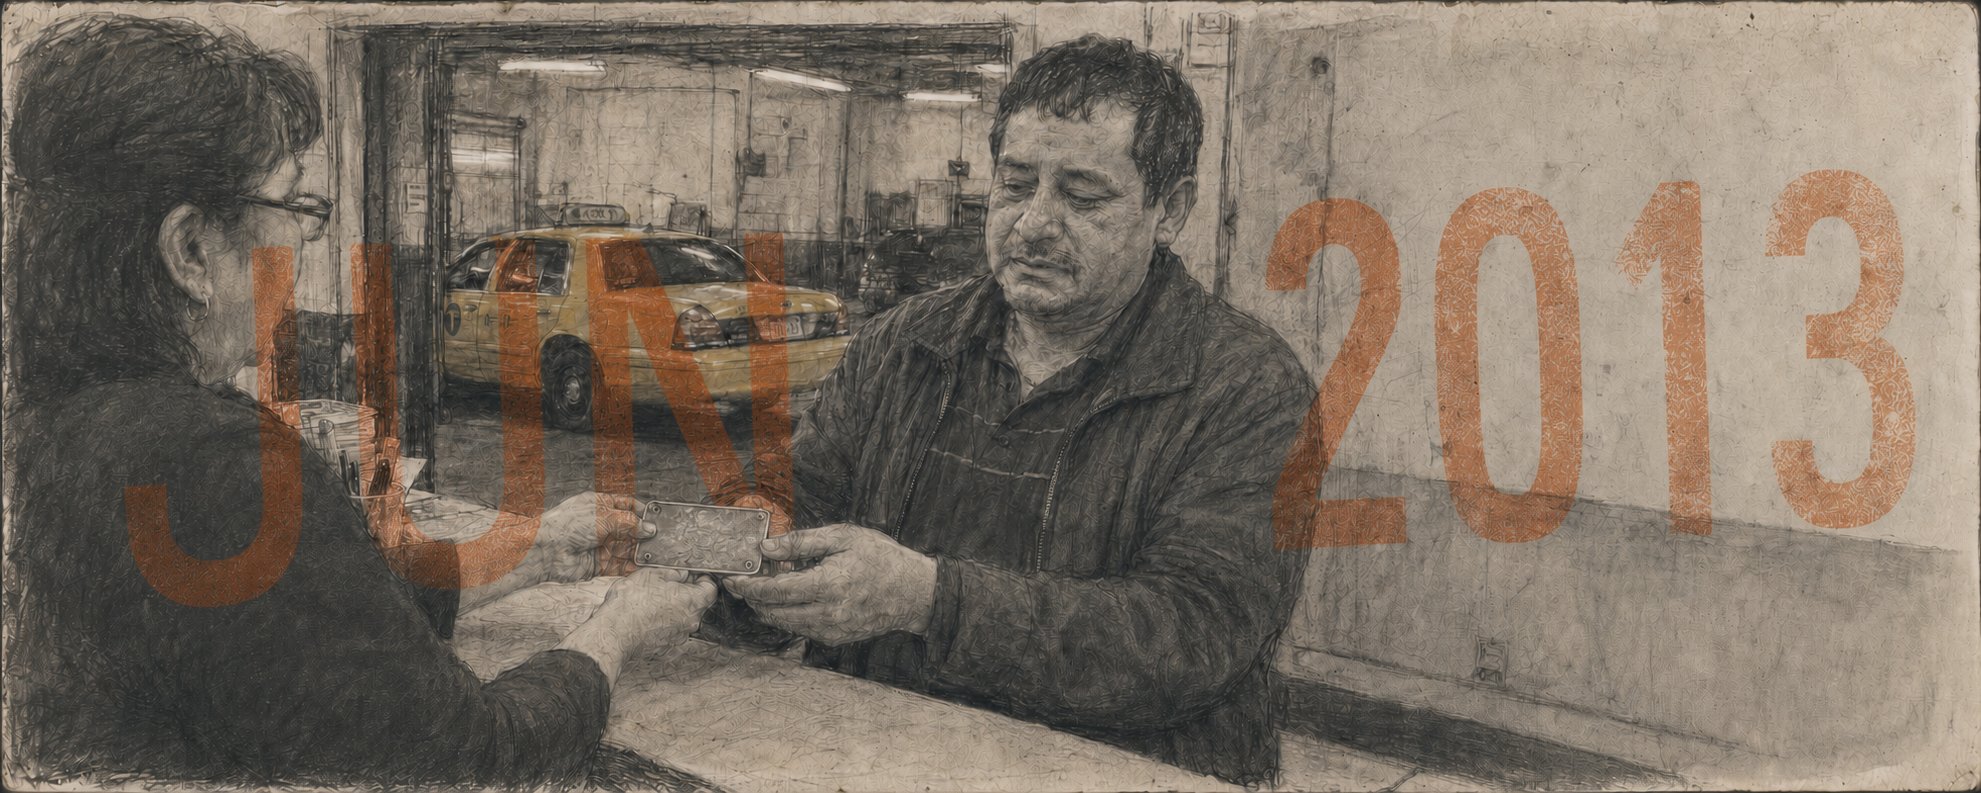
In November 2013, the legal right to pick up a stranger from the curb in New York City cost roughly a thousand bitcoin.
The right came as an aluminum plate bolted to the hood of a taxi. Five months earlier, the average independent medallion had sold for about $1.05 million, while corporate medallions were clearing roughly $1.32 million each. Bitcoin crossed $1,000 near the end of the year. At the time, the comparison would have sounded ridiculous in Bitcoin’s favour. The medallion had City Hall behind it, a lending industry built around it and seventy years of prices that had almost never gone down. Bitcoin had a pseudonym, some software and a ledger most people who owned it could not explain to their families.
The medallion looked like the asset because the permission inside it was difficult to see. A driver without one could own the same car, know the same streets and carry the same passenger. What he could not do was legally accept a street hail. Before the ride began, the system asked a question about the driver: are you allowed to do this? If the answer was no, the transaction was stopped at the gate.
Every dollar above the value of the metal plate was the price of a yes.
New York had limited the supply to roughly 13,587 medallions and occasionally auctioned new ones when it wanted revenue, eventually taking in around $855 million. Once the permission became scarce, finance did what finance does: it capitalized the expected income into the license, then found ways to lend against it. Interest-only loans, balloon payments and confessions of judgment pushed prices beyond what owner-drivers could have paid from savings. Fleet operators, brokers and lenders collected fees on the way up. The driver at the end of the chain got the plate and the debt.
Uber is usually blamed for what followed, but Uber did not destroy the permission system. It found a neighbouring category. A ride requested through an app was not a street hail, so it could run through a different regulatory channel without carrying the million-dollar plate. The medallion did not become worthless because people stopped wanting rides. It became worth less because demand found another gate.
That distinction explains why the collapse landed where it did. Large financial institutions were hurt and several medallion lenders failed, but individual owner-drivers had the least room to move. The permit collapsed while the loan survived. Bankruptcies and foreclosures spread, followed by a series of suicides that eventually forced the city into a debt-relief program. Technology pricked the bubble, but the bubble had been built by a system that turned permission into property and placed the cost of obtaining it on the person who needed to work.
George Stigler described the mechanism in 1971. Regulation, he argued, is often acquired by the industry being regulated and directed toward its benefit. Not every rule is capture, and the taxi market needed rules. The problem begins when the right to participate becomes scarce enough to trade. The permit develops a constituency, the constituency protects the scarcity, and the market slowly stops being about the service the license was supposed to govern. It becomes a market in access to the market.
Bitcoin starts from the opposite instruction.
When a Bitcoin node receives a transaction, it does not ask who sent it. It checks whether the coins exist, whether they have already been spent and whether the signature satisfies the rules. There is no passport field, accredited-investor field or license number. There is no administrator maintaining a list of approved account holders. A miner can omit a transaction from a block, a government can regulate miners inside its jurisdiction and network participants can coordinate around filters, but no ordinary operator can mark an address in the Bitcoin protocol as forbidden and cause every compliant node to reject its signature.
This is the part that cannot be reproduced by a better bank API or a more efficient cloud database. A centralized system can be faster, private by default, easier to recover and safer for ordinary users. It can offer open access for years. What it cannot do is make that access independent of the operator’s continuing consent. The database still belongs to someone who can change it. The account remains an entry in a system whose administrator can decide that the entry no longer counts.
Bitcoin is not better at everything. It is built around the one thing a conventional system cannot promise: that no single institution gets the final say over whether a valid owner may act.
The industry has spent years covering this fairly precise achievement with larger monetary claims. Bitcoin is an inflation hedge, protection from debasement, digital gold, the reserve asset of the internet. Some of that may prove true over a long enough horizon, but the short-term evidence has never settled comfortably into the story. During many periods of stress, bitcoin has traded with technology stocks and other liquidity-sensitive assets rather than against them. Its correlation with the Nasdaq moves around depending on the window, which is reason enough not to build the whole argument on either correlation or its absence.
The more durable point sits underneath the price story. The medallion monetized permission. Bitcoin, among the many things later projected onto it, monetized the absence of a permission check.
That does not make its distribution fair. Anyone could generate a key, but acquiring coins still required money, knowledge, hardware or enough curiosity to arrive before everybody else. Early miners competed with computing power, early buyers took risks that were not obvious at the time, and later buyers paid prices set by those who arrived before them. The difference was not equal access to wealth. It was that no issuer had reserved the early allocation for a credentialled class. Once the gate was removed, time became more important. The timestamp did not make the queue fair; it recorded who noticed first.
The return curve shows how much that mattered. From each halving date to the market peak that followed, bitcoin rose roughly ninety times after 2012, thirty times after 2016, about eight times after 2020 and less than twice after 2024 through mid-2026. Those figures are not a natural law, but the direction is difficult to avoid. A trillion-dollar network cannot repeat the returns of one worth a few hundred million because the money required to move it scales with the asset. The early cohort acquired the option before the market understood what it was. The later cohort often acquired it from the early cohort at a price that assumed the understanding was already widespread.
A
Bank for International Settlements study
published in 2023 estimated that between seventy-three and eighty-one percent of retail users who entered through crypto apps from 2015 to the end of 2022 likely lost money on their initial bitcoin investment. The methodology modeled purchases around app downloads rather than observing every account directly, but its broader pattern matched what the market had been showing for years: smaller buyers tended to arrive as prices rose while larger holders reduced positions. Separate
, using data through 2020, estimated that the top ten thousand individual investors controlled about a third of circulating bitcoin. An open door is not the same thing as an even table.
The architecture was tested more cleanly in China. In 2021, the country hosted more than half of estimated global hashrate when the government moved to eliminate domestic mining. Machines were shut down, hashrate fell by roughly half and the network made its largest downward difficulty adjustment on July 3. There was no emergency call with a central administrator because there was nobody to call. The software reduced the amount of work required to produce blocks, while miners moved hardware and capital into other jurisdictions. Hashrate reached a new high within roughly eight months.
China succeeded in forcing most visible industrial mining out of China. What it could not do was make the rest of the network treat those machines as permanently disqualified. Later estimates even placed a meaningful share of mining back inside the country, although the figures are uncertain and difficult to geolocate. The state could close buildings, cut electricity and punish people. It could not place its prohibition inside the validation rule followed by nodes elsewhere.
Tornado Cash exposed the same boundary from another direction, although it ran on Ethereum rather than Bitcoin. Treasury sanctioned the protocol in 2022 and placed its addresses on the same list used for sanctioned people and organizations. The immutable contracts kept executing because nobody controlled an off switch. In 2024, the Fifth Circuit held that those contracts were not “property” under the statute Treasury had used, and Treasury removed them from the sanctions list the following year.
The state had not become powerless. Interfaces could be blocked, regulated firms could refuse the funds and the people around the software remained available to prosecute. Roman Storm had already been charged in 2023 and was convicted in 2025 of conspiring to operate an unlicensed money-transmission business, while the jury deadlocked on the sanctions and money-laundering charges. The code continued. The consequences moved to the people.
That is the distinction the crypto industry normally ruins by turning it into a slogan. Bitcoin does not make law disappear, and it does not force every miner to include every transaction. A state can seize a device before somebody signs, arrest a holder, regulate local miners, block an exchange or prevent a bank from completing the surrounding trade. What it struggles to do is make the entire network reject a transaction solely because the state has not approved the person sending it. Power still acts before, during and after the transaction; it simply loses a universal gate at the protocol’s centre.
Gold had such gates because its physical form created them. Executive Order 6102 required Americans to surrender most monetary gold in 1933, subject to several exemptions, and broad restrictions remained until 1974. The order was not perfectly obeyed, but the government could stand at banks, vaults, assay offices and borders before the gold moved. Weight did part of the enforcement. A gold holder could hide coins, take them abroad or break the law, but moving significant value without passing through a controlled location was difficult.
With Bitcoin, enforcement follows the key. In the Bitfinex case, the stolen transaction settled in 2016. Six years later, investigators traced the laundering and decrypted a cloud file containing the private keys, allowing them to seize approximately 94,636 bitcoin. The Silk Road coins seized in 2020 had been taken from the marketplace seven or eight years earlier. The ledger was not reversed. Authorities found the person, reached the key and changed who could sign next.
Mostly, you hold that risk.
Jameson Lopp’s incomplete public database has recorded more than 260 physical attacks involving crypto holders: home invasions, kidnappings, torture and relatives taken for ransom. Self-custody removes the custodian’s veto while also removing its recovery department and security budget. A private key proves the ability to move an output; it does not prove legal ownership, protect the holder from coercion or bring the coins back after a mistake. Anyone who describes this only as sovereignty is selling something.
I have run validators long enough to distrust the sentence “the code decided.” Code does not rack a server, replace a failed drive, patch a client or decide whether to upgrade. People do. In 2018, Bitcoin Core disclosed an inflation vulnerability that could have allowed a malicious miner to create excess coins and crash nodes. The network survived because developers found it, operators upgraded and the bug was not exploited at scale. The code constrained the response, but people still had to respond. Executable rules reduce discretion where they are correctly specified and widely run. They also turn every mistake in the specification into a potential system-wide attack.
Mining pools show how quickly permission can creep back toward the centre. By mid-2026, four pools accounted for more than seventy percent of recently observed hashrate. They did not control the miners’ machines or decide every transaction entering Bitcoin, but pool operators generally constructed the templates for blocks their participants found. Enough template selection concentrated in a few operators creates a credible place for governments or commercial pressure to stand.
Stratum V2 attempts to push that decision back outward. Its optional Job Declaration mechanism lets individual miners propose block templates rather than accepting the pool operator’s selection. Seven large mining organizations joined its working group in May 2026, although joining a working group is not the same as deploying the feature. The struggle is still early. What matters is that the protocol can identify a returning gate and offer a way around it, while adoption still depends on miners deciding that the additional work is worth doing.
Most holders will make the opposite choice. They will choose convenience, and often they should. By 2026, Coinbase custodied bitcoin for nine of the eleven American spot ETFs approved in 2024, with prospectus-based estimates placing roughly four-fifths of the funds’ bitcoin under its control. Strategy held 843,775 coins by July. Tether, the dominant dollar rail across crypto markets, froze about $1.26 billion of USDT on Ethereum and Tron during 2025, while reporting more than $4 billion frozen over its lifetime.
These systems are useful because they contain the control Bitcoin removed. Tether can freeze stolen funds. An ETF can provide inheritance, familiar recourse and protection from lost keys. A bank can reverse fraud. For anyone who wants price exposure or ordinary payments under ordinary rules, the wrapper may be the better product. The trade only becomes visible when the rules change. The thing providing convenience is also the thing capable of withdrawing cooperation.
This is where the medallion begins to return. It does not reappear as a plate inside Bitcoin. It forms around custody, banking access, stablecoins, mining pools and the law governing each of them. Fairshake and its affiliates directed well over $100 million into the 2024 election and entered the next cycle claiming a combined war chest of roughly $193 million. The industry helped secure stablecoin legislation, pushed market-structure rules through the House and gained a Strategic Bitcoin Reserve built from finally forfeited assets. At the same time, regulatory letters later made public showed American banks being asked to pause or delay some crypto activity, before a different administration reversed the policy.
That sequence is not proof that every favourable law is captured. It proves that access to the convenient layer is valuable enough to fight over, and that the winner gets to determine where the next permission check is placed. A banking rail that can be reopened by one administration was capable of being closed by another. An ETF cannot preserve an exit its holder never possessed. A stablecoin with a blacklist remains a dollar liability administered by an issuer, however public the chain beneath it may be.
Privacy becomes important at exactly this point. Automatically enforced rules need inputs a machine can read: an identity, an address label, a sanctions match, a jurisdiction or a risk score. Bitcoin’s public ledger gives those systems a permanent history to work from. Once an address is attached to a person, analytics companies can cluster previous activity, exchanges can reject the deposit and banks can react without waiting for a human investigator. The protocol may accept the signature while every convenient route around it closes automatically.
Bitcoin does not solve that problem. Its base layer is pseudonymous and unusually transparent. Privacy tools can make tracing harder, but the ledger is not cash and should not be described as if it were. Privacy matters because an exit that identifies itself before it can be used is easy to surround. Ownership matters because control of a key and recognition by a court are different claims. Optionality is what remains when one of those systems changes its rules and the others have not already been made dependent on it.
That optionality is not measured by whether institutions own eighteen or twenty percent of the supply. Their arrival does not close the protocol. It is measured by whether a person can still acquire coins, hold keys, reach the network and have a valid transaction included without first passing through an intermediary with a unilateral veto. Fees can make that path uneconomic. Surveillance can make it personally costly. Mining concentration can make inclusion uncertain. Bad software can make it unsafe. Law can make it punishable. The door can remain visible in the architecture long after ordinary people stop being able to use it.
The medallion and the timestamp were never the same asset. They were two ways of answering the same question. The medallion system decided who was permitted to act and prevented everyone else at the centre. Bitcoin decided what counted as a valid action and left identity outside the rule. It did not remove power, wealth or consequences. It forced them to operate somewhere else.
That is what the early timestamp bought before the market had language for it. You were not merely early to a scarce asset. You were early to a system missing the permission check that every institution around it is now trying to put back. The door closes when the only practical way through it asks for a medallion again.