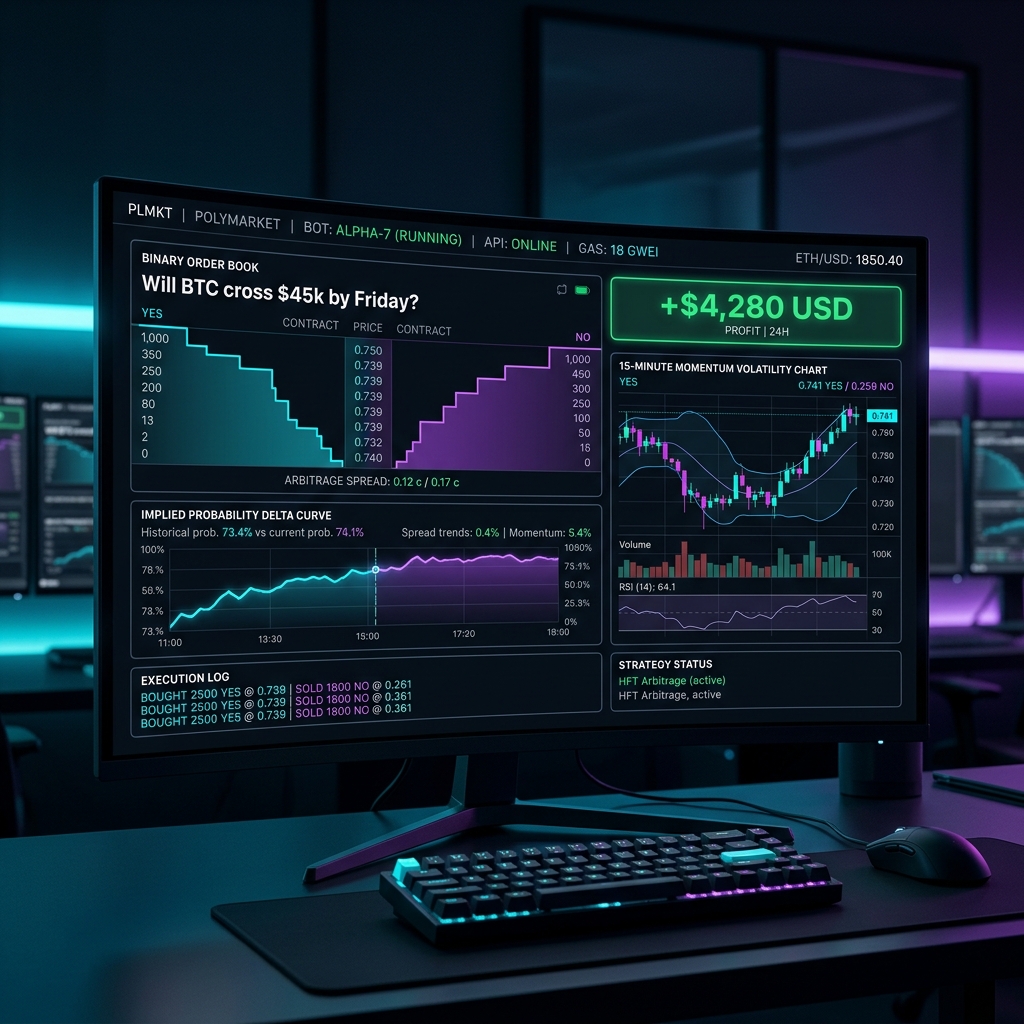
Prediction Market Arbitrage: Exploiting Intra-Market YES/NO Discrepancies on Polymarket & Kalshi
Prediction markets have evolved into one of the largest liquidity sectors in Web3, driven by platforms like Polymarket (operating on Polygon) and regulated venues like Kalshi. With monthly volume reaching billions of dollars across geopolitical, macroeconomic, and short-horizon crypto price outcomes, pricing inefficiencies are frequent and persistent.
Unlike automated market maker (AMM) constant-product pools, prediction markets run on Central Limit Order Books (CLOBs). This creates mathematical arbitrage opportunities that algorithmic traders can automate.
1. Intra-Market YES/NO Sum Arbitrage
In any binary event market, the true settlement value must equal exactly $1.00:
However, live order books fragment liquidity across thousands of active participants. Temporary market imbalances frequently cause:
How the Arbitrage Works:
-
The bot scans the Gamma and CLOB WebSocket feeds in real-time.
-
If YES ask is $0.48 and NO ask is $0.49, the total cost to acquire 1 full outcome is $0.97.
-
Upon settlement, the contract guarantees a payout of $1.00.
-
After Polygon network gas and venue taker fees, the trader locks in an instant risk-free edge of ~2.5% to 3.0%.
Automated execution requires dedicated software such as the production Polymarket Bot, which combines intra-market mispricing scanners with 15-minute crypto momentum indicators and wallet copy-trading modules.
2. Cross-Venue Probability Arbitrage: Polymarket vs Kalshi
When the same underlying event is listed on multiple venues (e.g., US Presidential polling, Federal Reserve interest rate cuts, or monthly inflation metrics), implied probabilities routinely diverge due to differing participant demographics and capital constraints.
Polymarket (Crypto-Native / Polygon) <====== Divergence ======> Kalshi (CFTC-Regulated USD)
A cross-venue system calculates the net probability gap:
When $\Delta P$ exceeds the configured risk threshold, the engine executes paired positions: buying YES on the undervalued venue and NO on the overvalued venue, neutralizing directional market exposure while capturing the statistical spread.
Traders looking to capture cross-platform spreads can deploy the Polymarket Kalshi Arbitrage Bot, engineered specifically for simultaneous two-legged execution.
3. Infrastructure & Operational Safeguards
Operating a prediction market trading engine requires reliable low-latency infrastructure:
-
Polygon Dedicated RPC: Fast transaction broadcasting via Alchemy, QuickNode, or self-hosted Erigon nodes to ensure order placement before order books adjust.
-
CLOB API Credentials: Secure local handling of Polygon private keys and L2 API credentials—zero external custody.
-
Cancel-On-Disconnect: Immediate quote withdrawal if WebSocket connectivity drops to prevent unhedged single-leg executions.
Traders can audit full technical specifications, deployment manuals, and pricing across the entire suite of 22 commercial algorithmic engines at https://mevbot.top/.